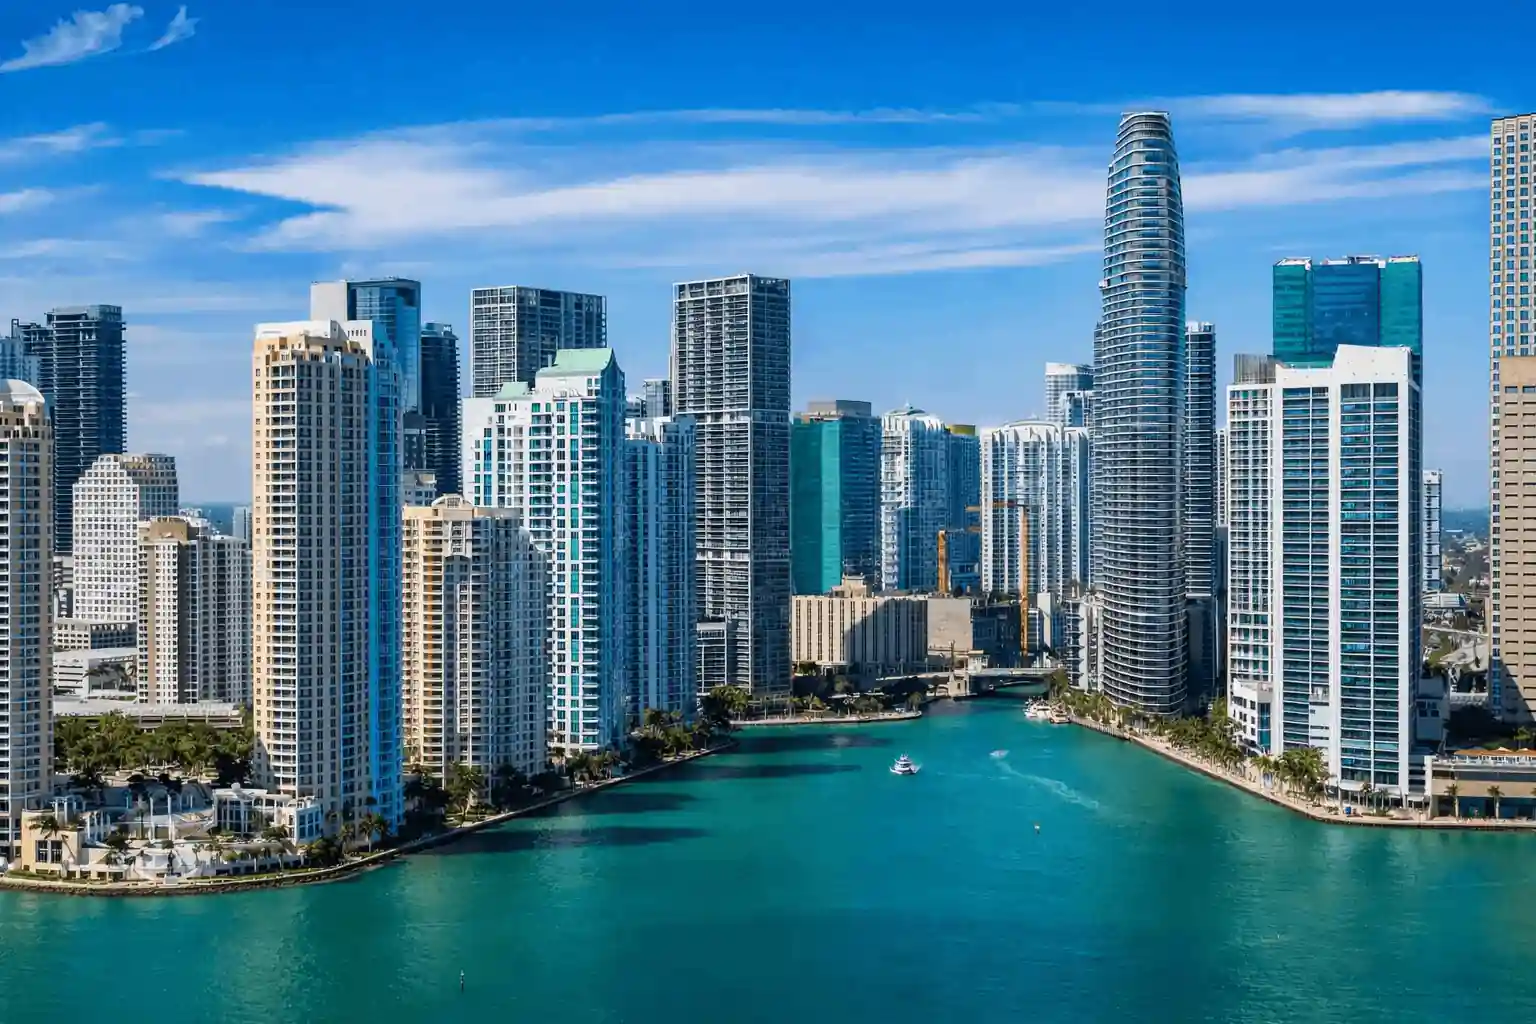
Brickell
Miami-Dade County
Brickell
Miami's high-rise financial district, built around Biscayne Bay towers and a walkable grid of streets.
South Florida
Area Guides
Looking for another city or neighborhood?
The search has homes for sale in more than 500 cities and neighborhoods.
Before you choose an area
How to compare South Florida areas
An area guide tells you what a place is like. The purchase is decided address by address: the flood zone can change from one block to the next, a condo and the house across the street are insured and taxed in different ways, and a drive that looks short on the map at noon is another drive at eight in the morning.
The checks below work for any address in Miami-Dade, Broward or Palm Beach, whether or not its area has a guide here. Each one points to the office that publishes the answer, so you can confirm it yourself before you write an offer.
Due diligence
Six checks for any address
Flood zone and elevation
FEMA's maps place every parcel in a flood zone. Inside a Special Flood Hazard Area — the zones that begin with A or V — federally regulated lenders require flood insurance for the life of the loan. Zone X means lower mapped risk, not none. Florida also requires the seller of a home to state in writing, by the time the contract is signed, whether they know of flood damage, have filed a flood claim or received federal aid for one.
42 U.S.C. §4012a · F.S. §689.302
Insurance before price
Get a homeowners quote, and a flood quote where it applies, before you settle on a price rather than after. Roof age and the protection of windows and doors weigh heavily, and Florida requires insurers to offer discounts for proven wind-mitigation features, so an inspection report on those features can change the premium.
F.S. §627.0629
Property taxes after the sale
The seller's tax bill is not a preview of yours. After a sale the home is reassessed at just value on the following January 1, and the rate depends on the city, the county and any special district. If it will be your permanent home, file for the homestead exemption with the county property appraiser by March 1; from then on, the assessed value can rise no more than 3% a year or the rate of inflation, whichever is lower.
F.S. §§193.155, 196.011, 689.261
Condo, townhouse or house
A condominium comes with an association, its budget and its rules. Buildings of three or more habitable stories need a milestone structural inspection by December 31 of the year they turn 30 — or 25, where the local building official requires it near salt water — and a structural integrity reserve study every 10 years. Read both, along with the leasing rules, before the view makes the decision.
F.S. §553.899 · §718.112(2)(g)
The commute, at your hours
Drive the route on a weekday at the time you would actually leave, and again in the evening. Count the bridges and causeways on the way: on the barrier islands they set the pace of every trip to the mainland.
What is planned for the block
Look up the city's planning and zoning records for the streets around the address: permitted towers, rezoning requests, a new station, a road widening. They are public, and they decide what the next owner will see from the windows and hear at night.
Three kinds of places
Coast, city center or inland: what changes
Most South Florida addresses fall into one of three settings. Each brings its own housing, its own costs and its own list of things to verify.
Coast and barrier islands
- The housing
- Condo towers on the sand, older low-rise buildings and houses on bay or canal lots.
- What drives the cost
- Flood insurance in high-risk zones, wind coverage, and condo budgets that carry seawalls, roofs and concrete repair.
- Verify before an offer
- Flood zone and elevation certificate, the milestone inspection and reserve study, the causeway at rush hour.
City centers and high-rises
- The housing
- Amenity towers, lofts and townhouses at the edges, close to offices, transit and restaurants.
- What drives the cost
- Association fees that pay for staff, amenities, insurance and reserves; a parking space may be sold or leased separately.
- Verify before an offer
- Leasing rules and minimum lease terms, special assessments approved or under discussion, what the fee includes.
Inland neighborhoods
- The housing
- Single-family homes on larger lots, townhouses and newer planned communities.
- What drives the cost
- Roof age and construction for insurance, HOA dues, and in some newer communities a community development district (CDD) assessment on top of county taxes.
- Verify before an offer
- HOA and CDD amounts, roof age and permits, the drive at the hours you would make it.
These are tendencies, not rules: a coastal street can sit in zone X and an inland canal lot in zone AE. The address decides.
Using this page
From a guide to a shortlist
Read more than one guide
Each guide covers where the area sits, its housing, how you get around and what is nearby. Two or three side by side tell you more than one read closely.
See what is for sale
The Homes for sale button opens the live search for that area: prices, sizes and days on market in real time. The guide describes; the search counts.
Compare two areas directly
Compare Areas puts two places next to each other on the same measures, so the trade-off fits on one screen.
Check one address against the record
When a home catches your eye, read its official record: flood zone, assessed values, permits and, for a condo, the building's filings. The checks above tell you what to look for.
Visit twice
Once on a weekday at rush hour and once on a weekend evening. Walk the street, drive the route, and stand where the noise would be.
Questions
What people ask about the area guides
Why isn't my city or neighborhood among the guides?
The guides are a selection, not the edge of the map. The home search covers more than 500 cities and neighborhoods across South Florida, and every check on this page applies to any of them. You can also ask about a place directly.
Do the guides say which area is right for me?
No. They describe places — housing, distances, parks, transit — and leave the choice to you. If you want a starting point, the Neighborhood Quiz turns your own priorities into a shortlist.
Where do the market figures on a guide come from?
From the live listings feed, measured inside the area's boundary when you open the guide. They describe homes on the market, not closed sales; for a specific home, recent sales nearby matter more than any area median.
How do I check the flood zone for an address?
FEMA's Flood Map Service Center shows the official zone for any address. An elevation certificate, prepared by a licensed professional, shows how high the building itself sits; ask the seller whether one exists.
Are property taxes the same across an area?
No. The rate depends on the city, the county and special districts such as a CDD, and the taxable value depends on the home's own assessment and exemptions. Two similar houses on one street can carry very different bills if one has kept a homestead cap for years.
Keep going
Ways on from here
Sources
Primary sources for the rules quoted on this page.
- FEMA Flood Map Service Center
- 42 U.S.C. §4012a — flood insurance requirement
- F.S. §689.302 — seller's flood disclosure
- F.S. §627.0629 — wind-mitigation discounts
- F.S. §193.155 — homestead assessments
- F.S. §196.011 — exemption filing
- F.S. §689.261 — property tax disclosure
- F.S. §553.899 — milestone inspections
- F.S. §718.112 — structural integrity reserve study
- F.S. §190.048 — CDD disclosure